Beyond M&A: How GP Solutions Is Becoming a Distinct Investment-Banking Product for Private Markets
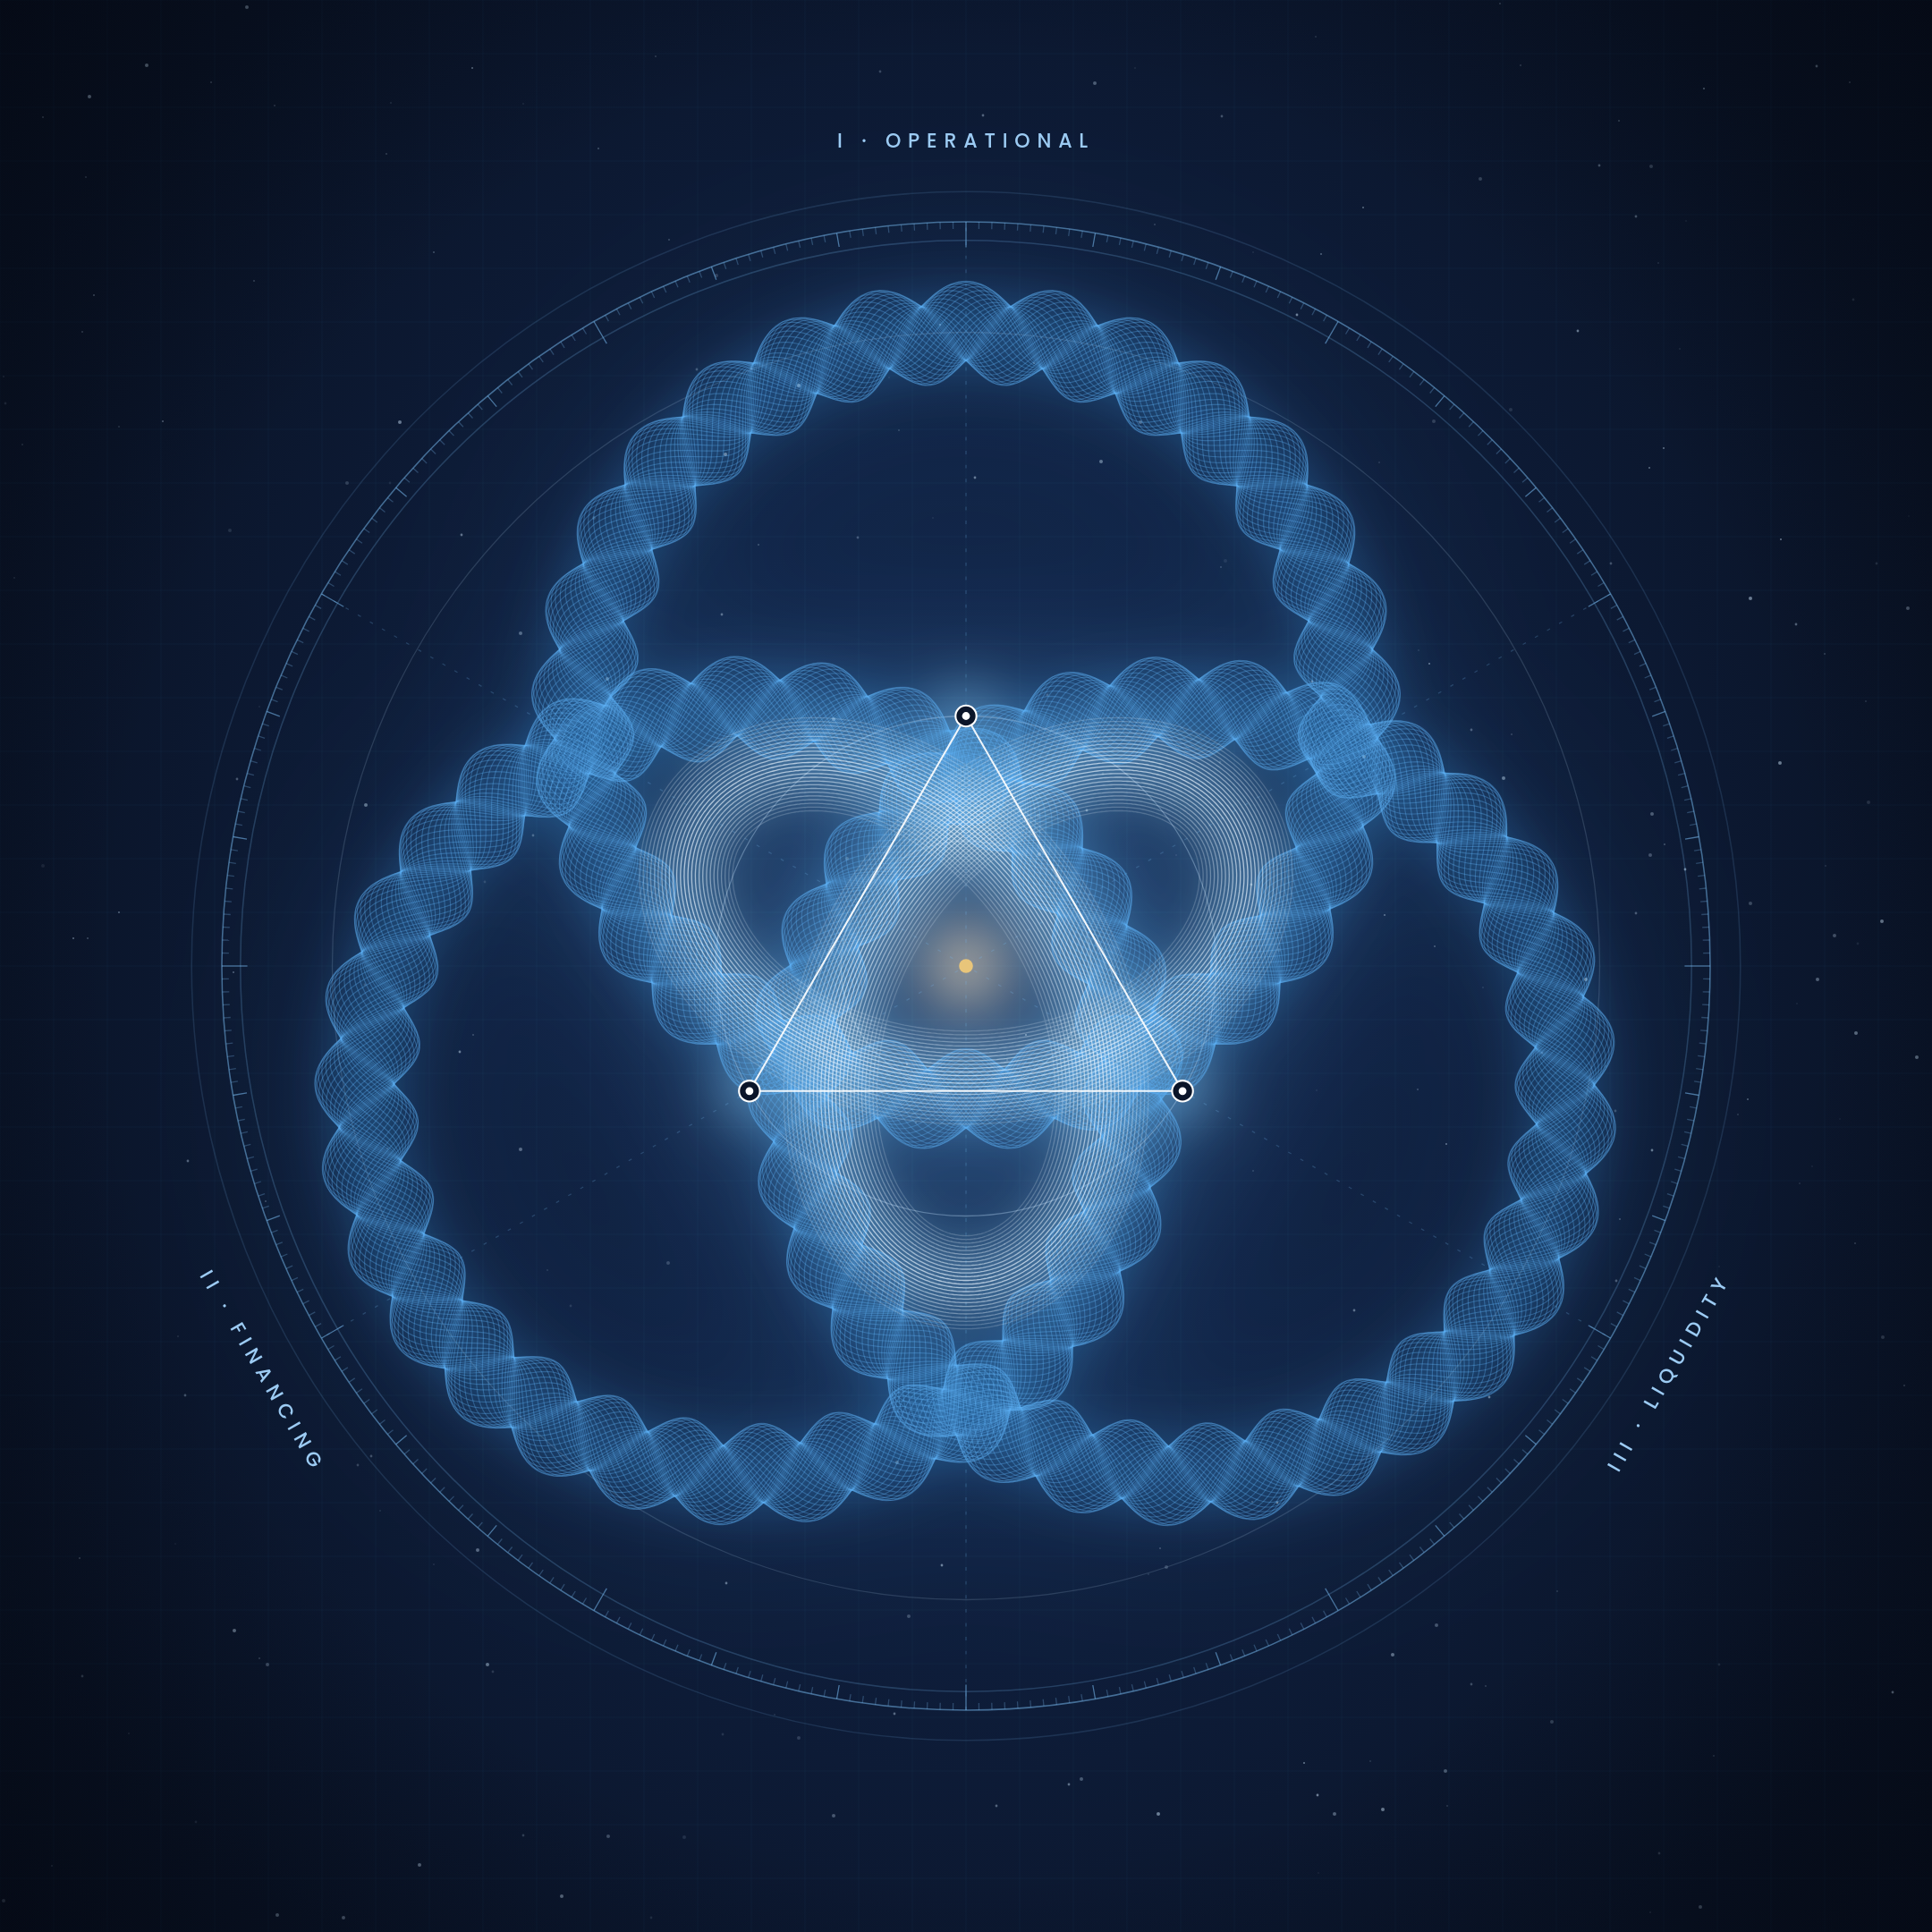
Private markets are about more than mere profit maximization - they are about long-lasting value creation and impact through operational, financing, and liquidity alignment. - Author’s Opinion
A force to be reckoned with. Private markets are no longer a peripheral alternative investment instrument, and they are growing:
Data shows that private markets took an 11% share of all global assets under management (AUM) in 2024, which amounted to $135 trillion. Moreover, they are projected to grow to 13% out of $200 trillion AUM by 2029. In nominal terms this means growing from almost $15 trillion to $26 trillion in just 5 years - a staggering 75% increase.
On top of that, we are experiencing a severe liquidity crisis as limited partners (pension funds, insurance firms, endowment funds, sovereign wealth funds, etc.) have invested heavily ever since the COVID-19 pandemic. Meanwhile general partners, i.e. fund managers, lag behind the needed distribution capacity of realized returns, since they simply struggle to sell in the extremely high valuation environment.
Exiting a position, for an equity firm, traditionally means going down one of three paths: sale to a strategic (or corporate) buyer, sale to a financial buyer (or a sponsor), or an Initial Public Offering (IPO).
Now, let us take a closer look of the current market dynamics in tables:
Statistics from 2025 shows how buyout backed exits grew 47% in value to $717 billion, however their number dropped 2% and around 32,000 companies, valued at $3.8 trillion, remain trapped only on books. While distribution to limited partners (LPs) accounts for 14% of the net asset value (NAV), remaining under 15% for the fourth year in a row, and IPOs rose by 36%, remaining a minor route.
This is why the calls for the development of the “Fourth Exit Option” have grown louder, and it lies within the Private Capital Advisory industry.
But what is Private Capital Advisory and who does it? Well, the classification is murky, as the industry is still not fully standardized across banks, divisions, and roles, but it has five core components:
-
Primary Fundraising (usually Private Funds Group);
-
LP-Led Secondaries (usually LP-led Secondary Advisory);
-
GP-Led Secondaries (usually GP Solutions in a purely capital recycling sense);
-
Structured Finance & Coverage Advisory (both corporate & sponsor clients);
-
Sponsor banking (usually Financial Sponsors Group).
This new strategy, which we will discuss in detail, covers capital recycling, meaning the redistribution of liquidity, which allows markets to function the way we know them. Its primary focus is not capital formation or capital structuring, rather providing this much needed liquidity in order to widen the choices of market participants, who require tangible distributions to cover their immediate needs.
And the “new” option, which has been filling the gap left by the core three exit methods and has become increasingly mainstream in the last years: General Partners (GP)-led secondaries, or the way we will refer to them in the article, GP Solutions. It allows for a relocation of the asset while also providing LPs a choice and an opportunity at the same time - either stay in the game, or abandon ship through the use of a continuation vehicle.
The practice consists in moving the asset from an older fund to a new one still managed by the same sponsor. At this point existing LPs can choose whether to receive a stake in the new vehicle equally big to the position in the previous fund, or cash out the stake and interest. In the latter case, the influx of new investors provides the liquidity needed to satisfy those immediate liquidity needs.
This new methodology reflects broader market trends and environmental changes in the very fabric of society as a whole, dictated by two factors: the end of cheap debt and the wave of inflated valuations post-Covid.
Firstly, from the 2008 crisis up to the immediate pre-pandemic period, interest rates fell, offsetting rising debt burdens in the US, this trend reversed during Covid, as the Federal Reserve saw its balance sheet going from $4 trillion to 9 by 2022 (inflationary pressure), contemporarily, in Europe, the war in Ukraine caused an energy shock that led inflation to grow to 10.6% by October 2022.
The response by the Fed was a consecutive series of policy rates hikes to 5.25%/5.5% by July 2023. Since then the pressure has not eased enough to revert the effects, as events such as the war in Iran, with correlated instability, both political and economical, especially regarding fuel prices, have caused US inflation to 3.4% as of August 2026, which prompted the Fed to raise rates again to 3.75%/4% following a 25-basis-points approved at the Federal Open Market Committee on September the 16th 2026.
The results are clearly identifiable: the median US buyout in 2025 is valued at around 12.5 times the EBITDA, however sponsor funding, unlike in the past, has to be composed of higher levels of equity as debt is more expensive because of the aforementioned reasons.
12.5x EBITDA
At the same time post-Pandemic tendency and leftover cash invested caused a spike in valuation of companies as well as IPOs’ expected values for revenue: from around $100-250 in the 2010s to around $500 to $700 millions today. This means that it is also harder than ever to go public, as investors are becoming increasingly cautious, when investing during IPOs and require more stable annual recurring rates of return (ARR), not to mention the rising risk premium and the drained investor funds from the AI frenzy at the moment.
The result is that companies bought at 2021 prices are hard to sell avoiding a loss, slowing exits’ numbers, hence leaving LPs with less returns in cash and liquidity to reinvest. This is why limited partners right now are becoming extremely picky, in which funds to invest, and general partners fall under increasing pressure to sell, or at least to pay up the LPs somehow.
Because of the increase of GP-led secondaries volume, banks have adapted by creating GP Solutions teams within their Private Capital Advisory groups, and this system differs both from traditional M&A and private capital fundraising. Here it is about enabling the financial sponsor to extend the duration of its presence and remain as an advisor within the asset firm, while improving its operational, financial, and governance standing, as opposed to flipping hands and starting the next chapter for the business.
In the meantime, there are many caveats worth mentioning, which make GP Solutions teams this much more crucial for such a transaction. GPs are present on both the sides of the process, creating a modern problem which depicts one of the most prominent conflict of interests issues in corporate law, spanning from pricing to carried interest, as their decisions include selecting investors for the new financial vehicle, establishing both a fair price to offer and the conditions of the fund while providing existing LPs with acceptable liquidity options.
This is where GP Solutions teams could play the intermediary role, while easing the pressure on the GP, who has to offer both the best sell & buy prices. Having discussed that, we may now begin with a perfect recent instance of private capital advisory building bridges, whilst allowing capital markets to function properly and meeting the actors’ liquidity needs.
While living in 2026 and mentioning artificial intelligence, we hear more often than not the phrase “sovereign AI”. For instance, Mistral AI, Europe’s leading large language model (LLM), is giving its best to sell the idea to investors in order to increase the capital flow in digital infrastructure. If sensitive data is stored and processed in infrastructure that is physically and legally under EU jurisdiction, that can reduce the risk that a third-country government can compel access under its own laws. What if such a government encourages malicious actors to test the cyber security strength of its rivals and tries to exploit its vulnerabilities?
Now, imagine a scenario where such malicious activity compromises internal enterprise agents, which could do tens of thousands of unauthorized actions within a company’s cloud and data infrastructure within just a few seconds and could delete or extract it all before the cyber security team could even blink. This is what Zuma, Saviynt’s enterprise AI identity security platform, could prevent. A modern solution to a horrifying modern issue, which could cost the world billions, and even trillions, if not addressed with utmost caution.
This is one of the reasons why this company is such a lucrative investment and investors are fighting to cling onto the bandwagon and not miss out on any of the private company’s enormous potential. A bit more on the underlying asset itself: Saviynt is an American enterprise cloud-native identity security platform company founded and led by CEO Sachin Nayyar. The company provides unified access governance, risk management, and identity security across modern enterprise environments.
And when we dig a little deeper into the metrics, we see a whole world of opportunities, which will explain the pickle of its financial sponsors.
Since Saviynt is a private firm, we do not have the full P&L, but a snapshot of the financial situation has been established, which is truly mesmerizing. After the recent conclusion of its series B funding round, which amounted to $700 million, a valuation of approximately $3 billion has been reached during the announcement of Carrick Capital’s transfer of its Saviynt shares in a new continuation vehicle (CV). For context, Carrick Capital is an American growth-equity B2B software and SaaS orientated buyout fund with a $2.08 billion AUM after the oversubscription of its new CV.
Furthermore, Carrick disclosed that the firm’s ARR has expanded 30x from around $10 million at Carrick’s initial Series A entry to $300 million ARR, supported by 80%+ annual bookings growth and a 96% customer retention rate. This led to a realisation of 11x Gross MOIC / 10x Net MOIC on Carrick’s initial invested capital for the LPs which chose to cash out instead of rolling over to the new CV. A 30x ARR growth between funding rounds with an expected 80% growth in sales for a company this size is marvelous.
Indeed, like hitting the jackpot in Vegas on a Thursday night, when you have to pay your mortgage by the end of the week.
This is the moment when the GPs realize that they have to sell the asset in the current unfavourable macroeconomic environment. Or does it? Well, it for sure has to satisfy the needs of its LPs. In 2026 the DPI, or the distributed to paid-in capital, is the only metric that now matters for them. But there has to be an explanation why…
Outside of the obvious where DPI is harder to argue with than unrealized NAV (net asset value), since its cash vs. assets, we have a few main other sticking points, which make the current situation quite unsettling for the LPs.
-
Slow exits - For several years because of the higher rates, which translate into higher borrowing costs, valuation gaps and weaker IPO & M&A markets extend holding periods. The GP wants to sell high, as it costs a lot to reach that point, but the potential buyers, both public and private, see it as marketing and overselling it to save their skins.
-
Capital recycling needs - LPs need actual cash to recycle into new funds. A pension fund might theoretically have excellent PE performance, but if its GPs keep calling capital while returning little cash, it eventually runs into a liquidity problem.
-
Becoming overweight - Strictly regulated fund mandates allow up to a certain percentage of high risk assets as a part of the LP’s portfolio. And if the assets do not get realized and grow in value too quickly, they will have to be partially or entirely liquidated. The same goes the other way around. If the public markets underperform or get partially wiped in a mini market correction, the same overweight logic would apply and the private assets will have to be sold to carry out the mandate’s requirements.
It seems as if LPs are becoming quite picky with whom they are going to do business with. Because if you want to survive in this dog-eat-dog society, you have to be able to realize, not just on paper, some astronomical results in order to garner their attention. Though the same goes with your bank advisors, which is where FSG comes into play.
To achieve such “astronomical results” you might need “astronomical expertise”, which lean PE teams sometimes might lack in certain niche areas, which is when the Financial Sponsors Group in many investment banks levels the playing field. Sponsor bankers, as they are called, act as the connection and relationship manager between the financial sponsor client and the wider investment bank, which could in turn offer a range of coverage and advisory services.
With this out of the way, deal sourcing, connections, and operational alpha become the main drivers of success in the private markets industry. To clarify, operational alpha is the bankers’ exquisite way of calling operation alignment through sponsor stewardship, i.e. the sponsor acts with accountability for entrusted funds, efficiency in resource use, financial planning and a high degree of ethics).
Nevertheless, this does not define GP-LP relations. They are significantly more complicated and involve a complex web of conflicts of interest, especially when we talk about approving a continuation vehicle and involving the transfer or selling of assets at a certain valuation. This will be described in more detail later.
It was mentioned that the financial sponsors are in a pickle right now, especially in Saviynt’s case, as we have established that the asset is worth holding onto. This is a classic “winner’s curse” case.
But first, why the hurry?
A closed-end private fund has a finite life. It is typically around 10 years with up to a two year extension. The timer starts ticking the moment the first close has been made during the fundraising period, which means that it is before the first capital call, when an investment has been found. The process is slow and drags on usually for 12 to 18 months after the first close. Then the investment period continues for up to 6 years after the first close and the harvest begins as early as year 5 and as late as the end of the extension period of the fund. Though sometimes this is not enough…
The “winner’s curse” is when a fund has bought an asset early and has gone through the whole hassle of the streamlining its operations to create genuine value and in turn returns, as if it was delayed gratification, but then the fund’s life comes to an end or the LP requests to have its capital distribution, which might mean to sell the asset prematurely or under hasty or outright bad conditions. In this case, the fund will sell and the buyer will inherit the proceeds of the hard work and that “delayed gratification”. Though a solution has been found some time ago and, due to the current economic conditions, it is becoming increasingly relevant as a mainstream investment banking tool. This is GP Solutions.
In the first half of 2026, single-asset continuation vehicles (SACVs) comprise 53% of all GP-led secondary market activity globally. And this is namely the case of the Carrick-Saviynt transaction, as the sponsor did not seek to prematurely sell the asset. Saviynt transferred into the CV at an implied Enterprise Valuation of approx. $3.0 billion, which transfer is actually our only source of the current implied valuation of Saviynt. The valuation was further anchored by a concurrent $700 million Series B growth financing round led by KKR, with participation from Sixth Street Growth, TenEleven, and Carrick Capital (as part of the continuation fund transaction).
The CV transaction itself, though, was the interesting part of the equation. When funding a continuation vehicle to extend the life of an asset, you offer the legacy Carrick Fund II LPs a choice - you either roll over, meaning to stay and to transfer their original stake into the new CV like moving a folder from one drawer to another, or exiting, which could also result into an LP-led secondary transaction, where the LP sells its stake to another investor instead. But when an LP wants to exit, it will want to receive the cash it has been waiting for patiently for years, while the GP does not sell the underlying asset. Instead, the GP finds new investors on the secondary market, who would commit money to give liquidity for the existing legacy LPs, while maintaining cash balance.
This is when it gets complicated as a conflict of interest imminently arises. The fund manager inherits the fiduciary duty of the LP as it has to uphold the values and principles of sponsor stewardship and come up with the highest possible valuation for the legacy LPs to receive as much as possible. At the same time, the GP has to also fulfill its new fiduciary duty and come up with the lowest possible valuation for new investors to enter as to enable them to earn as big of a reward as possible, while funding the new CV, which enables the continuation of the asset ownership itself. This is why certain safeguards are needed, with one of them being Baird Capital's financial advisory role to Carrick to ensure a third-party independent valuation of the asset.
For the CV itself, Coller Capital, a British investment firm specializing in secondary market transactions for PE & PC with a $50 billion AUM, and HSBC Asset Management were the lead and co-lead new investors, respectively, together with meaningful commitments of Carrick’s own GPs, assuring with “skin in the game”, and some of Carrick Capital’s own funds pooled an approx. $600 million of capital commitments. This is an impressive sum for a fund with a total AUM of a bit more than $2 billion.
But how was the money spent?
Out of the $600 million, $255 million were used as primary equity during the series B funding round of Savient to fund employee tender offers in order to retain talent, buy back some of the illiquid Savient private stock options, and to reward the hard work of the talented staff behind the firm’s success. This is actually quite noble for a PE fund to do… We could only assume that the rest of the money in the CV mostly used to pay back the legacy LPs, which chose to liquidate and realise their enviable net 10x MOIC from the gross 11x MOIC.
All of this shows immense potential for growth and a CV enables this both for the investor and for the company. Imagine a scenario where Carrick is forced to sell as there were no such things as SACVs. It will likely sell it to a huge IT services conglomerate, which will likely reduce R&D, fire staff, and increase short-term gains to please shareholders on public markets due to quarterly reporting, which will also remove a possible threat to their business models. A truly horrible scenario for innovation.
This is why GP Solutions is so important. It enables high-growth companies in innovative industries to scale at their pace for longer periods of time without needing to tap into the public markets, which will require serious scrutiny from regulators. Same goes for long-term projects that require significant capital investment, but will in due time lead to reliable cash flows and continuous economic benefit for local communities. Examples of such sectors could include deeptech, software, healthcare, lifesciences, infrastructure, energy, and all of the private market financial sponsors such as private equity, private credit, and all of their subsets (growth equity, venture capital).
But what justifies the creation and the funding of a continuation vehicle? What are private markets for more broadly?
As said in the beginning, private markets are not just transactional alpha. Well, at least not anymore, as the industry has been forced to rethink how it earns its IRR. The newly achieved focus on value creation due to the evolving economic conditions are then primarily observable via the interpretation of the “Trinity Alignment”:
The continuation vehicle enabled Saviynt to retain sponsor stewardship and expertise, improve the social aspect of the sustainability equation through the employee tender offer, and gain additional time for value creation.
In Saviynt, Carrick leveraged its proprietary Approach to Building Value (ABV) to guide ARR expansion from $10 million to $300+ million without organizational disruption. Carrick’s ABV methodology further includes a three pillar structure - refining the sales strategy, improving market positioning, and scaling operations.
As a counterargument to CVs, operational continuity can entrench underperforming management teams or insulate GPs from the scrutiny a traditional exit strategy would entail. In our case, fortunately, Saviynt has a brilliant C-Suite to steer its daily operations and achieve impressive growth results.
Through the involvement of the CV in the series B funding round, the establishment of a strong implied valuation, and the primary equity re-investment check (Carrick Capital’s largest single investment so far) into the firm with a meaningful GP stake in it are clear signs of trust in the business, which offer an opportunity for growth and talent retention.
The aspect of the employee tender offer also falls in this category as it not only incentivises workers to be more motivated, but in this case it further supplied fresh equity capital suited to Saviynt's next growth phase without requiring it to further dilute its ownership or finance the overdue investment in human capital via debt.
A way to counter this is by acknowledging that in sub-optimal CVs, financing alignment breaks down when sponsors use NAV loans or fund-level preferred equity to artificially inflate legacy distribution metrics (DPI), burdening the asset with high-cost leverage. How would believe that a 12% or a 15% interest rate on a liability costing millions would not be the brightest of ideas. Carrick funded 100% of the injection with primary equity, though, which ticks this box too.
This is probably the strongest argument in favour of creating continuation vehicles within private markets. It allows for capital recycling to fulfill the needs of both the LPs and the GPs.
It allows the General Partners to retain ownership of the asset and escape the “winner’s curse”. In the meantime, it presents a choice to the LPs, which could present an opportunity for even more proceeds, which will in the end contribute to the fiduciary obligations of the LPs to their beneficiaries. It resolves LP differences by offering either a cash-out, which could also be done via an LP-led secondary sale of stake to a third-party investor, or a rollover into the new CV, which accommodates differing LP liquidity needs.
On the other hand, liquidity alignment is often asymmetrical and really difficult to achieve with many conflicts of interest. Selling LPs face information asymmetry, compressed decision windows (sometimes only 20 days), and potential price suppression if the GP seeks a low entry valuation for the CV. Rolling LPs are frequently squeezed by forced fee increases or carry resets if the true status quo option as in the former fund is omitted. In the new CV for Saviynt this remains blurry as the management fees, carry crystallization, and other fees were not fully disclosed.
There is no perfect investment and no perfect investment banking product or service. The continuation vehicle is no different from this financial market rule. Because the GP sits on both sides of a continuation vehicle transaction, acting as sell-side fiduciary for the legacy fund and buy-side manager for the CV, structural conflicts arise. Such examples could be the extrapolated implied valuation of the CV’s underlying asset(s), management fee & carry extensions, or stapled commitments of secondary investors, which are being granted access to the GP’s flagship fund if they access a low-ball valuation for the CV investment.
To ensure transactions are benefiting cashing-out LPs without harming rolling LPs, the private markets industry relies on the ILPA (Institutional Limited Partners Association) Principles, the CFA Institute Ethics Standards, and corporate law principles. And in order to uphold these principles a governance committee established within a private fund, composed of a selected group of Limited Partners (LPs), primarily tasked with reviewing and approving GP conflicts of interest, valuation methodologies, cross-fund transactions, and key LPA (Limited Partnership Agreement) waivers. This is the LPAC, the Limited Partner Advisory Committee. Sometimes though even the LPs themselves are within a conflict of interest, which is when third-party advisors are brought in to carry out valuation and other advisory services.
Now, having gone through the main issues of CVs, it is important to also mention that this is not the only instrument, which is covered by the GP Solutions group in investment banks and advisory firms. In fact, there are also multi-asset continuation vehicles, tender offers, strip sales, preferred equity, Fund / NAV solutions (could also be partly covered by Structured Finance teams), and other GP-led liquidity transactions. These are important tasks, which the division covers, but in a broader sense it may include services from the traditional services, which fulfill the traditional requirements for one of the three exits, mostly M&A and ECM, but also Financial Sponsors Group, Structured Finance, and Leveraged Finance.
Basically a versatile instrument, which is becoming increasingly mainstream, especially in some growth or capital intensive sectors.
Generally speaking, the Private Capital Advisory industry is experiencing a profound shift, and the new generation of bankers will need a cross-dimensional set of skills in order to achieve the desired results. This is generally described in three layers - Underlying Asset Economics, Fund Economics, and Investor Economics.
At the underlying asset level, advisers still need conventional corporate-finance skills such as valuation, M&A, leverage, and exit analysis skills. At the fund level, however, they further require to grasp fund life, NAV, carried interest, management fees, DPI, LP liquidity, and portfolio construction. Finally, at the investor level, they must understand why different LPs, secondary buyers, credit investors, and co-investors have different return requirements and liquidity horizons.
This is why PCA is so interesting. It sits at the cross section of these three areas of understanding. In the meantime private markets are moving from an alternative ownership model into a genuinely developed and mainstream part of capital markets, where barriers for non-institutional investors are persistently degrading.
Moreover, the rapid growth in the GP Solutions, and the Private Capital Advisory industry as a whole, is only accelerating. Due to the current macroeconomic conditions, including a sovereign debt crisis, fossil fuel supply shocks, increased protectionism, rising risk premiums as well as high valuations and investor caution with new IPOs, a concoction of downward pressure on traditional exit methods and investment instruments has forced the even quicker development of private markets.
All in all, we may now return to the “Trinity Alignment” framework for one last time. New investment instruments and tools will require new methods to regulate the financial and capital markets to ensure the resilience of our economies. In the meantime, however, people have to be vigilant and seek to improve the world rather than be opportunistic out of its hardships. This is why private market alignment with value creation and impact will remain the core principle sponsor stewardship.